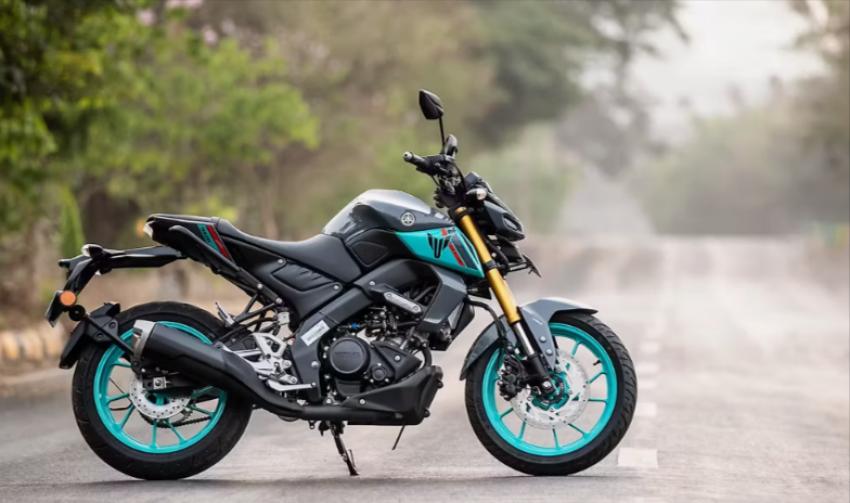
The Yamaha MT-15 V2 is a sporty 155 cc motorcycle that encourages riders to look beyond basic commuting. For many Indian buyers, the bigger question is how to pay for it without compromising regular expenses. A two-wheeler loan can distribute an upfront purchase across monthly instalments, but the convenience has a measurable financial cost. Before borrowing, evaluate the exact MT-15 variant, your likely annual running expense and the full repayment amount. The right offer is the one that fits the household budget after insurance, servicing and other commitments, not simply the smallest advertised EMI.
Confirm the model and what the showroom is quoting
The MT-15 V2 uses a liquid-cooled 155 cc engine with a six-speed gearbox and features such as upside-down front forks and traction control on relevant India-market versions. Yamaha lists a power output of 18.4 PS and torque of 14.1 Nm on its official sales material. However, equipment, colour choices and dealer stock can change over time. Identify the actual vehicle offered by model year and variant, then request a quotation separating ex-showroom price from registration, insurance and optional accessories. This breakdown helps prevent financing an unwanted add-on by accident. A lender may value the vehicle differently from the dealer invoice, so ask how the loan principal is determined.
Start with an affordable initial payment
A larger down payment reduces the amount financed, but using every available rupee for the booking can leave an owner vulnerable to unexpected bills. Preserve a reserve for household essentials, medical requirements and necessary travel. Then decide what amount can be paid without borrowing from other sources. Compare a loan with a smaller principal against an offer featuring a low initial payment and longer repayment period. The second option might feel attractive at purchase, but it usually builds a higher interest burden if the rate is otherwise similar. Confirm whether any dealer deposit is adjustable against the final price and when cancellation deductions apply.
Understand what determines the monthly EMI
Loan principal, annual rate and tenure govern a standard reducing-balance EMI. A longer schedule can lower the monthly figure while extending the period during which interest accrues. When comparing quotations, use the same term and financed amount; otherwise an apparently cheaper rate can conceal a different repayment structure. Ask for a full amortisation schedule showing monthly due dates, total interest and total amount payable. If a rate is described as flat, establish the comparable effective borrowing cost before deciding. Eligibility and rates depend on lender policy, applicant income and credit profile, so figures from another buyer are not a reliable personal forecast.
Charges beyond the headline interest percentage
Processing charges, documentation fees, stamp duty where applicable and additional insurance may all affect what you ultimately spend. Request an itemised cost sheet and distinguish optional services from contractual conditions. Find out whether part payment is allowed, whether foreclosure charges apply and how a failed auto-debit is handled. The agreement should clarify overdue interest, recovery procedures and steps for obtaining a closure certificate. Dealers may help with paperwork, but the legal lender remains the organisation named on the loan agreement. If an offer cannot be explained in writing, do not accept it simply to secure a preferred motorcycle colour.
MT-15 running costs need their own allowance
The ownership budget must cover fuel, tyres, scheduled services, chain lubrication, brake pads and the occasional unexpected repair. Riding style and traffic influence fuel efficiency, while sportier tyres can carry a different replacement expense from a small commuter's tyres. Allocate some money each month for consumables rather than treating service bills as surprises. Genuine riding equipment, including a well-fitting helmet and suitable gloves, should be purchased without relying on leftover cash. Factor in insurance renewal separately from the loan EMI. A monthly instalment that consumes the entire spare income may turn routine vehicle upkeep into another source of borrowing.
Compare finance channels fairly
A dealership-arranged offer may be convenient, especially when documentation is processed during the booking. A bank or non-bank lender may provide different rates, charges or eligibility criteria. Collect at least two written quotes and match them for principal, duration and the treatment of insurance. Consider customer support, digital repayment access and how quickly the lender provides a no-dues confirmation at the end. Avoid applying indiscriminately to numerous lenders purely to search for a marginal rate difference. Check whether interest calculations or promotional pricing change if delivery is delayed. Written quotations matter more than general advertising language.
What happens after disbursal?
Verify that the repayment account, instalment amount, first due date and financed vehicle details match your signed documents. Keep copies of the agreement, disbursal statement and all receipts. Track automatic payments rather than assuming every debit succeeds. If income becomes temporarily irregular, contact the lender before missing an instalment and ask about any available remedies; do not stop paying without agreement. Late payments can affect borrowing records, while unpaid charges may complicate closure. When the obligation ends, obtain evidence that the hypothecation or charge has been released according to applicable registration procedures. Good records protect the owner long after the motorcycle leaves the showroom.
When is financing an MT-15 V2 a reasonable choice?
Proceed when the bike suits your routes, the down payment leaves savings intact and the total repayment is acceptable. Review the agreement alongside other ongoing EMIs, not in isolation. If a longer term is necessary just to make the instalment possible, consider a cheaper variant, a larger initial payment after saving or postponing the purchase. Responsible finance should support riding enjoyment without creating pressure every time a salary arrives. Check repayment flexibility before committing. Request complete repayment figures before agreeing to dealer finance.