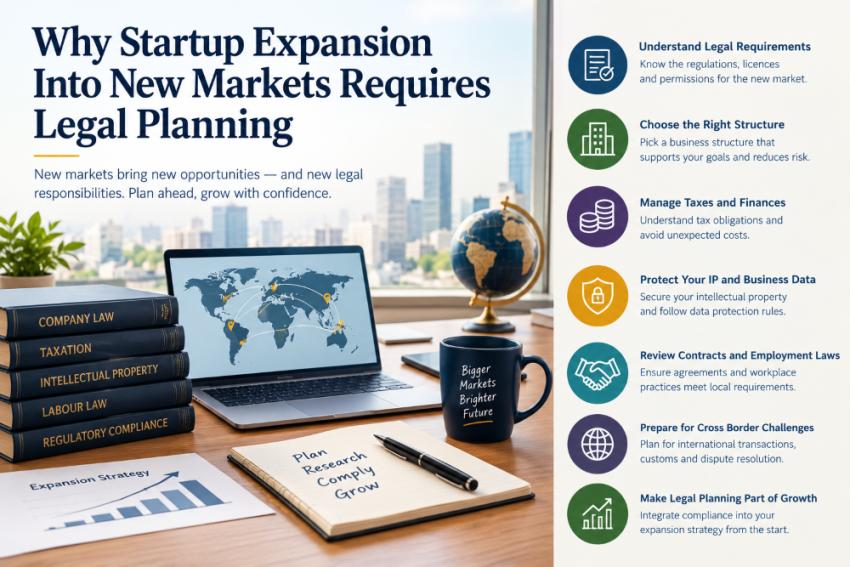
Expanding into a new market is an important milestone for any startup. It can create opportunities to reach new customers, increase revenue and build a stronger business presence. Whether a company plans to enter another Indian state or establish operations in an overseas market, expansion often brings new commercial possibilities. However, growth also introduces legal responsibilities which founders may overlook when focusing on sales, partnerships and customer acquisition. A business model which works well in one location may require changes before it can operate lawfully in another. Local regulations, taxation rules, licensing requirements, employment laws and contractual practices can differ considerably between markets. Without proper preparation, a startup may face unexpected expenses, regulatory delays or disputes with customers and business partners. Legal planning helps founders identify these risks before they interfere with expansion. It also provides a clearer framework for making commercial decisions and managing the company's long term growth.
Understanding the Legal Requirements of a New Market
Every market has its own legal and regulatory environment. Even when a startup offers the same products or services, its obligations may change depending on where it operates and how it enters the market. For example, a business selling products online may need to review consumer protection requirements, product standards, tax obligations and rules governing digital transactions. A company opening a physical office may face additional requirements involving premises, local registrations and employment. International expansion can introduce further complexity. Businesses may need to examine foreign investment rules, customs requirements, import restrictions and local laws governing commercial operations.
Founders should begin by identifying the activities they intend to undertake in the new market. They should then determine which permissions, registrations and compliance measures apply to those activities. This assessment should take place before the company commits significant resources to marketing, recruitment or infrastructure. Early legal research can reveal restrictions which may affect the feasibility or cost of the proposed expansion.
Choosing the Right Business Structure
One of the first decisions involves determining how the startup will establish its presence in the new market. Depending on the jurisdiction and business model, the company may operate through its existing entity, appoint a distributor, enter a joint venture or establish a separate legal entity. Each option has different implications for ownership, liability, taxation and management.
For example, working through a local distributor may reduce initial costs and simplify market entry. However, it can also limit direct control over customer relationships and sales activities. Establishing a separate entity may provide greater operational independence, but it can involve additional registration formalities, reporting duties and administrative expenses. Founders should also consider how the proposed structure will affect future investment. Investors may examine ownership arrangements, control rights and the relationship between the parent company and any newly established entity. A suitable structure should reflect the startup's commercial objectives, available resources and anticipated growth. It should also allow the business to adapt if its initial market entry strategy changes.
Managing Registrations, Licences and Regulatory Compliance
Entering a new market may require more than registering a company. Depending on the sector and location, a startup may need specific licences, tax registrations, local permissions or regulatory approvals before beginning certain activities. Requirements can be particularly important in regulated sectors such as financial services, healthcare, food production and education. Digital businesses may also face rules concerning consumer rights, electronic transactions and the collection of personal information. For startups expanding within India, obligations can vary according to the nature of the business, the states involved and the activities performed. Businesses should examine applicable central, state and local requirements rather than assuming an existing registration covers every new operation.
Startup registration services for new markets may help founders understand the formalities involved in establishing a business presence and completing relevant registration procedures. However, registration is only one part of legal readiness. Companies must also maintain ongoing compliance, renew applicable licences and keep their corporate records accurate. A compliance calendar can help the business track filing deadlines, licence renewals and reporting obligations. Assigning responsibility for these tasks reduces the risk of missed deadlines as the company grows.
Reviewing Taxation and Financial Obligations
Expansion can change a startup's tax position. New sales channels, employees, warehouses or business locations may create additional registration and reporting requirements. For instance, an Indian business expanding its sales across states should assess the applicable Goods and Services Tax requirements, including registration, invoicing and return filing obligations. Businesses entering foreign markets may need to consider local corporate taxes, indirect taxes, withholding requirements and customs duties.
International operations can also raise questions about permanent establishment, transfer pricing and the tax treatment of payments between related entities. The precise implications depend on the relevant jurisdictions, the nature of the activities and applicable tax treaties. Founders should assess these matters before finalising pricing and revenue projections. A market may appear commercially attractive until additional taxes and compliance expenses are included. Early tax planning helps businesses estimate the true cost of expansion and avoid financial surprises after operations begin.
Protecting Intellectual Property and Business Information
A startup's intellectual property may become more valuable as its customer base expands. Its trademarks, software, designs, inventions and proprietary processes can help distinguish its products from competing offerings. However, intellectual property protection is territorial in many respects. A trademark registered in India, for example, does not automatically provide equivalent protection in every overseas market. Before expansion, founders should assess whether important brand names and other protectable assets require registration in the intended jurisdiction. They should also check for existing rights which could create conflicts with local businesses.
Technology companies must pay particular attention to licensing arrangements. An agreement permitting software use in one territory may not authorise commercial distribution elsewhere. Similar concerns arise when a startup relies on third party technology, copyrighted material or licensed content. Data protection is another important consideration. Businesses collecting customer information must understand the rules governing its use, storage, disclosure and international transfer. Clear intellectual property and data management policies can protect valuable business assets while reducing the risk of disputes or regulatory action.
Understanding Local Contracts and Employment Laws
Successful market entry often depends on relationships with local suppliers, distributors, service providers and employees. However, contracts and employment practices suitable for one market may not be appropriate in another. Commercial agreements should define payment terms, delivery responsibilities, performance standards, confidentiality obligations and procedures for resolving disputes. Founders should also examine exclusivity provisions and termination rights before entering long term arrangements with local partners.
Employment requirements need similar attention. Recruitment may involve rules concerning wages, working hours, employee benefits, workplace safety and termination. International expansion can also raise immigration and work authorisation questions. A startup which hires quickly without reviewing local employment obligations may face disputes, penalties or unexpected operating costs. Seeking advice from startup lawyers for market expansion can help founders assess local legal requirements, structure commercial agreements and identify risks before committing to a new market. Legal review is particularly valuable where the business will operate across multiple jurisdictions or enter a regulated industry.
Managing Cross Border Transactions and Disputes
Overseas expansion can introduce additional contractual and financial risks. Businesses may need to make payments in foreign currencies, transfer funds between entities or enter agreements with parties subject to different legal systems. Founders should establish how international contracts will be interpreted and enforced. The governing law, dispute resolution mechanism and jurisdiction clauses can influence the cost and complexity of resolving disagreements.
Currency fluctuations and delayed payments may also affect commercial relationships. Agreements should address payment deadlines, acceptable currencies and the consequences of non performance. Where goods cross international borders, businesses should review customs documentation, import restrictions and applicable trade requirements. Depending on the product and destination, additional certification or product compliance obligations may apply. Planning for these issues before launch can reduce uncertainty and help the startup respond more effectively when commercial problems arise.
Integrating Legal Planning Into the Expansion Strategy
Legal planning should not be treated as a final administrative step after the business strategy has been decided. It should form part of the expansion process from the beginning. Founders should assess the legal and regulatory requirements alongside market demand, operating costs and available resources. This allows them to identify barriers early and adjust their plans before substantial expenditure takes place.
The review should also continue after entry. New regulations, changes in business activities and growth in transaction volumes may create additional obligations. Regular compliance reviews help ensure the company's practices remain appropriate as operations develop. Clear internal responsibilities are equally important. Founders should know who manages regulatory filings, contractual approvals, employment matters and data protection. Accurate records make it easier to demonstrate compliance and respond to investor due diligence. By integrating legal considerations into business planning, startups can make more informed decisions and avoid treating compliance as an obstacle to growth.
Conclusion
Expanding into new markets can provide startups with valuable opportunities, but successful growth requires more than identifying customers and increasing sales. Business structures, registrations, taxation, intellectual property, contracts and regulatory compliance can all influence whether expansion remains commercially sustainable. Legal planning helps founders understand these obligations before they become costly problems. It also supports better financial forecasting, stronger commercial relationships and greater confidence among investors and business partners. The most effective approach is to assess legal requirements early, obtain appropriate advice and review compliance as the business evolves. With careful preparation, startups can enter new markets with a clearer understanding of their responsibilities and a stronger foundation for sustainable growth.